Your Insurance Detective › Open enrollment 2027
When does open enrollment start for 2027 health insurance? Raise your hand now and I call you first.
Open enrollment for 2027 plans starts November 1, 2026 in most states. Pick by December 15 for a January 1 start. Premiums are going up again. Most people wait until the deadline and scramble. You don't have to.
Put your name on my early list. In October I reach out, look at your situation, and have a game plan ready before the rush. No cost, no commitment, no hard sell.
By Dick Tracy, independent health insurance broker, NPN 20414610, licensed in 25 states · Published September 3, 2026 · Updated October 13, 2026
✅ You're on the list.
I'll reach out in October with a game plan before open enrollment opens. Keep an eye on your phone and your inbox. It'll be me, Dick Tracy, not a call center.
Can't wait that long? Grab a free 30-minute call right now and we'll start early.
📅 Book a call nowOr text me directly: 716-503-1113
Quick answer Open enrollment for 2027 health insurance runs November 1, 2026 through January 15, 2027 in most states, and December 15, 2026 is the last day in most states to pick a plan that starts January 1. New York, New Jersey, and California run through January 31, 2027. A federal rule that would have cut the window off at December 15 was thrown out by a judge in June 2026, so the longer dates stand for 2027. Meanwhile marketplace insurers asked for a median 15 percent increase for 2027. Raising your hand means I put you on my early list and reach out in October, before the window opens, so your decision gets made with time to spare instead of at the deadline. It costs nothing and commits you to nothing. I educate, you decide.
Who's on the other end when you raise your hand
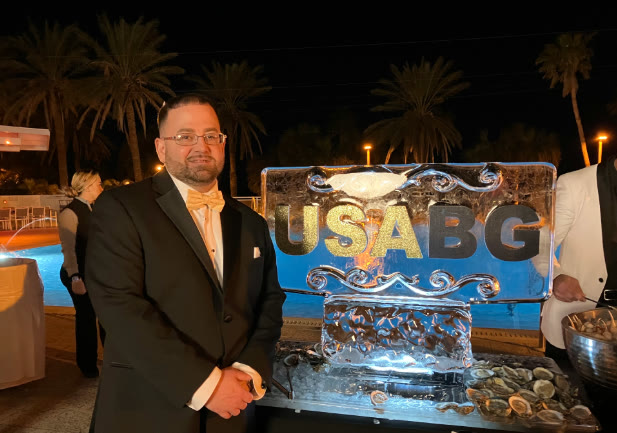
Me. Richard "Dick" Tracy. Real name, real job.
Independent health insurance broker · NPN 20414610 · Licensed in 25 states · 80+ carriers · Buffalo, NY
This is not a lead form that sells your name to ten agencies. Your hand goes into one place: my own client file. The person who calls you in October is the same person whose card is spinning on the left, and I'm the one who picks up when you call 716-503-1113. No call center, no rotating "specialist," no pressure.
I spent years on the healthcare side before I became a broker. Billing codes, prior authorizations, the real price behind the "allowable" rate. So there's no gag clause on me. I'll tell you the tips, the tricks, and the traps, and I'll tell you when something is not for you.
2027 open enrollment dates by state (the 25 states I'm licensed in)
Thirteen of my states use HealthCare.gov, and they all share the same window. The other twelve run their own marketplaces and set their own dates. In most states, pick a plan by December 15 if you want coverage on January 1. Massachusetts, New Jersey, and California give you a little longer, and Maryland is expected to, as the table shows.
| State | 2027 open enrollment | Pick by, for a Jan 1 start |
|---|---|---|
| Alabama, Arizona, Delaware, Florida, Indiana, Michigan, North Carolina, Ohio, South Carolina, Tennessee, Texas, West Virginia, Wisconsin (HealthCare.gov) | Nov 1, 2026 to Jan 15, 2027 | Dec 15, 2026 |
| New York | Nov 1, 2026 to Jan 31, 2027 | Dec 15, 2026 |
| New Jersey | Nov 1, 2026 to Jan 31, 2027 | Dec 31, 2026 |
| Pennsylvania | Nov 1, 2026 to Jan 15, 2027 | Dec 15, 2026 |
| California | Nov 1, 2026 to Jan 31, 2027 | Dec 31, 2026 |
| Virginia | Nov 1, 2026 to Jan 29, 2027 | Dec 15, 2026 |
| Massachusetts | Oct 23, 2026 to Jan 23, 2027 | Dec 23, 2026 |
| Connecticut | Oct 23, 2026 to Jan 15, 2027 | Dec 15, 2026 |
| Maryland | Nov 1, 2026 to Jan 15, 2027 | Dec 31, 2026 (expected) |
| Colorado, Georgia, Kentucky, Maine | Nov 1, 2026 to Jan 15, 2027 | Dec 15, 2026 |
Dates per healthinsurance.org (updated August 10, 2026); the New York, New Jersey, Pennsylvania, California, Massachusetts, and Maryland rows checked against each state's own marketplace on October 2, 2026. Where a state has not posted its 2027 cutoff yet, the table shows the date it has used before. States can still adjust; I re-check this table every month through the window. Some options outside the marketplace, like a pre-established ERISA group plan, are not tied to these dates at all.
What happens after you raise your hand
Name, email, phone, zip. That's it. No medications, no doctors, no paperwork yet. Just a hand in the air.
A quick call or text from me. I ask the detective questions: your doctors, your prescriptions, your income picture, what bugged you about this year's plan.
Every door you can walk through, with the math next to it. Marketplace, group merge, add-ons, or "keep what you have." You pick.
Why now and not December
Two things are stacking up at once. Everyone's decision lands in the same few weeks, and 2027 rates are going up again in most places. If your renewal letter last year made you say "the math doesn't math," do not count on the next one being kinder. The people who do best every year are the ones whose plan was already picked before November 1.
(Jan 31 in New York)
marketplace insurers, all 50 states
Western New York's big three (they asked for 14% to 24%)
Sources: enrollment dates per healthinsurance.org; national median from KFF, August 4, 2026; Western New York requests per New York Department of Financial Services filings as reported by The Buffalo News, June 12, 2026; approved rates per the NYS Department of Financial Services, September 4, 2026. The national median is requested increases, not final approved rates.
What my clients say (2 min)
“We used Richard for our family’s health insurance and it’s been amazing. He’s saving us thousands of dollars a year. We’ve got our whole family using him, even our married children.”Mike Cornelius, family client
“Dick helped our family find an alternative to COBRA. He listened to what we needed, ran all the numbers and thoroughly explained everything.”Ellen M., Google review
“Extremely knowledgeable! Great guy, and wonderful service. Meeting with him costs you nothing and could save you thousands!”Meagan M., Google review
Who this is for
Individuals, families, self-employed people, and small businesses who pay for their own health insurance and want a real look at every option before the rush. If you're on a 1099, own a business, lost a subsidy, got a renewal that made no sense, or just never had anyone explain what you're paying for, raise your hand. If you're turning 65, I write Medicare supplements too (not Medicare Advantage, and I'll tell you plainly why).
Common questions about open enrollment 2027 and raising your hand
When does open enrollment start for 2027 health insurance?
November 1, 2026 in most states. That is the first day you can pick a marketplace plan for coverage starting January 1, 2027. Three state-run marketplaces open earlier: Connecticut and Massachusetts on October 23, 2026, and Idaho on October 15. Everywhere else, including New York, Florida, Texas, Pennsylvania, and California, the door opens November 1.
When is the deadline for 2027 open enrollment?
January 15, 2027 in most states, but the date that matters more is December 15, 2026: in most states that is the last day to pick a plan that starts January 1. Enroll between December 16 and January 15 and your coverage starts February 1, which leaves a January gap. Some state-run marketplaces run longer: New York, New Jersey, California, and Rhode Island go to January 31, 2027, Virginia to January 29, and Massachusetts to January 23. Pennsylvania ends January 15, and Idaho closes earlier, on December 15. A few states also give you longer for a January 1 start: December 23 in Massachusetts and December 31 in New Jersey and California.
Did open enrollment get shortened to December 15 for 2027?
No, not for 2027. A 2025 federal rule (the Marketplace Integrity and Affordability rule) tried to end open enrollment on December 15 nationwide, but a federal judge vacated that part of the rule in June 2026. So the 2027 window still runs through January 15 in most states and longer in several state-run marketplaces. If that ruling gets reversed on appeal, the dates could change, which is one more reason to get your decision made early instead of at the deadline.
When is open enrollment for health insurance in New York for 2027?
New York's marketplace runs November 1, 2026 through January 31, 2027 for 2027 coverage, the same window it has used every year, and the state has published those dates. Plan on December 15 for a January 1 start; that has been New York's cutoff year after year. New Yorkers also have options outside the marketplace, like a pre-established ERISA group plan, that are not tied to the enrollment window at all.
Will health insurance premiums go up in 2027?
Yes, almost everywhere. KFF's August 2026 review of insurer filings across all 50 states and Washington, D.C. found a median proposed increase of 15 percent for 2027 marketplace plans, the second straight year of double-digit increases after a 20 percent finalized median for 2026. In Western New York, the three big carriers asked the state for 14 to 24 percent more on individual plans, and on September 4, 2026 the New York Department of Financial Services approved 0 to 12.2 percent, depending on the carrier. Statewide, insurers asked for 20.6 percent and the state approved 6.0 percent. The national figure is still requests; regulators usually trim them, but the direction is not in doubt.
What if I miss open enrollment for 2027?
You can still get marketplace coverage if you have a qualifying life event: losing job coverage, moving, getting married, having a baby, or turning 26 and aging off a parent's plan, each of which opens a 60-day special enrollment period. Outside of that, the marketplace is closed until the next fall. Some options I work with are not tied to the window at all: a pre-established ERISA group plan can be started any month, and in states that allow private underwriting, so can an underwritten individual plan. Raising your hand now is the simplest way to never be in that spot.
Is Medicare open enrollment the same thing?
No. Medicare's annual enrollment period is October 15 to December 7 every year, and it is for Part D drug plans and Medicare Advantage. I do not sell Medicare Advantage, and I will tell you plainly why when we talk. I do write Medicare Supplement (Medigap) plans, which can be applied for any time of year. In most states they are guaranteed during your first six months on Part B, with health questions after that. In New York, insurers have to accept your application all year, with no health questions.
What does raising your hand actually mean?
It means you want a look at your 2027 health insurance options before open enrollment opens. It is not a quote request and it is not an application. You give me your name, email, phone, and zip code. I put you on my early list. In October I reach out, ask a few detective questions about your doctors, your prescriptions, and your budget, and have a game plan ready for you before November 1. Then you decide.
Does raising your hand cost anything or commit me to anything?
No and no. In every state I work in, the carrier pays the broker, so your premium is the same whether you use me or not. I never charge a fee. Raising your hand does not sign you up for anything, and your information stays with me: I am one licensed broker, not a call center, and I never sell or share a lead list. If the plan you already have turns out to be the right one, I will tell you to keep it. I educate, you decide.
I am self-employed and not in New York. Can you still help me?
Yes. I am licensed in 25 states: Alabama, Arizona, California, Colorado, Connecticut, Delaware, Florida, Georgia, Indiana, Kentucky, Maine, Maryland, Massachusetts, Michigan, New Jersey, New York, North Carolina, Ohio, Pennsylvania, South Carolina, Tennessee, Texas, Virginia, West Virginia, and Wisconsin. Everything happens by phone or Zoom with the plan documents on the screen. Self-employed people are the ones I help most: in states that allow private underwriting, a healthy 1099 earner often has more doors than New York does, and a pre-established ERISA group plan works in all of them.
Same price as going it alone. No fee, no hard sell. Thirty minutes and you'll know every door you can walk through.
Or grab a time right here
Pick a slot below and it lands on both our calendars. No phone tag, no hard sell. I educate, you decide.